Blog

  • Why Every Caregiver Should Help Their Parents Set Up a Lasting Power of Attorney

    Why Every Caregiver Should Help Their Parents Set Up a Lasting Power of Attorney

    You already juggle your own work, your own family, and the growing responsibility of looking after your parents. You help them book their polyclinic appointments, you sort out their CHAS card renewals, and you might even assist with their CPF nominations. But there is one critical document that many caregivers overlook: the Lasting Power of Attorney, or LPA. Without it, you could find yourself locked out of your parents’ affairs at the very moment they need you most.

    Key Takeaway

    A Lasting Power of Attorney lets you legally manage your parents’ money and healthcare decisions if they lose mental capacity. Without one, you may face a costly, stressful court application. This article explains why caregivers must act now, how the LPA process works in Singapore, common pitfalls to avoid, and where to find help. Start the conversation today.

    What Is a Lasting Power of Attorney and Why It Matters for Your Parents

    A Lasting Power of Attorney is a legal document that lets your parents appoint someone they trust usually you, their adult child to make decisions on their behalf if they lose mental capacity. This could happen due to dementia, a stroke, a severe accident, or any condition that affects their ability to think clearly.

    In Singapore, the LPA is governed by the Mental Capacity Act. It covers two main areas:

    • Personal welfare decisions: Where your parents live, their daily care, medical treatment, and even life-sustaining treatment.
    • Property and affairs decisions: Managing their bank accounts, paying their bills, selling their HDB flat, handling their CPF savings, and dealing with their investments.

    Without an LPA, if your parents lose mental capacity, nobody gets automatic legal authority to act for them. Not you. Not your siblings. Not even your parents’ spouse. You would need to apply to the Office of the Public Guardian for a deputyship order, which is time-consuming, expensive, and emotionally draining.

    The Very Real Cost of Not Having an LPA

    Imagine your mother has a stroke and can no longer communicate. Her monthly bills are due. Her CPF payouts need to be managed. She may need to sell her flat to fund her care. Without an LPA, you cannot legally touch any of her assets.

    You would have to apply to the Family Justice Courts to become her deputy. This process can take several months and cost thousands of dollars in legal fees. You also need to submit medical reports, court documents, and attend hearings. All this while you are already stressed about her health.

    “Many families come to us only after a crisis. By then, the parent has already lost capacity, and the family is stuck with a lengthy court process. Setting up an LPA earlier would have saved them time, money, and heartache.” — Alvin Goh, estate planning lawyer with 15 years of experience in Singapore.

    The message is clear. Do not wait for an emergency. Help your parents set up their LPA now, while they are still mentally sound and can sign the document themselves.

    What Happens When a Parent Loses Capacity Without an LPA

    Here is a practical step-by-step look at what you would face if your parent loses capacity and has no LPA in place.

    1. Crisis hits. Your parent suffers a stroke, is diagnosed with dementia, or has a serious accident. Doctors confirm they lack mental capacity.

    2. You realise you have no legal authority. Banks freeze your parent’s accounts. You cannot pay their utilities or housing loans. You cannot access their CPF.

    3. You apply for a deputyship order. You must file Form 1 with the Family Justice Courts. You need a doctor’s report confirming your parent’s incapacity, a court application fee, and likely a lawyer.

    4. You wait. The application process takes 4 to 6 months on average. In the meantime, bills pile up. You may need to use your own money to cover their expenses.

    5. The court decides. Even if you are approved, the court places restrictions on your powers. You must submit annual reports on how you have managed your parent’s finances. This adds ongoing cost and paperwork.

    All of this can be avoided with an LPA that costs a small fraction of a deputyship application.

    The Three Common Mistakes Caregivers Make with LPA

    Many well-meaning families stumble when setting up an LPA. Here are the most frequent errors and how to avoid them.

    Mistake Why It Happens How to Avoid It
    Delaying until it is too late Caregivers think they have plenty of time. Dementia or stroke can strike without warning. Set a deadline. Book the LPA appointment within the next 30 days.
    Choosing the wrong donee(s) Parents pick a child who lives overseas or is not good with money. Discuss openly. Pick someone responsible, local, and willing to serve.
    Not understanding the two forms Form 1 covers property and finances only. Form 2 covers both property and personal welfare. Use Form 2 for full coverage. Many families regret not including welfare decisions later.

    How to Help Your Parents Set Up Their LPA in Singapore

    The process is simpler than most people think. Here is a clear step-by-step guide for caregivers.

    Step 1: Have the conversation. Talk to your parents about why an LPA matters. Use real examples. Share stories of families who struggled without one. Be gentle but honest.

    Step 2: Choose the donee and replacement donee. The donee is the person your parents appoint to make decisions. This is usually you or a sibling. The replacement donee steps in if the first donee cannot act. Your parents must trust these individuals completely.

    Step 3: Complete Form 1 or Form 2. Download the forms from the Office of the Public Guardian website. Form 1 covers property and affairs only. Form 2 covers both property and personal welfare. Most experts recommend Form 2.

    Step 4: Get the form certified. A qualified certificate issuer, such as a psychiatrist, accredited mediator, or lawyer, must certify that your parents understand the LPA and are not being coerced.

    Step 5: Register the LPA with the Office of the Public Guardian. Submit the certified form online or in person. There is a registration fee. As of 2026, the fee is $50 for Form 1 and $75 for Form 2. Citizens aged 65 and above enjoy a fee waiver of $50 for Form 2.

    Step 6: Store the LPA safely. Keep the registered LPA in a safe place. Tell your family where it is. You may also want to share a copy with your parents’ bank and lawyer.

    For more context on how the LPA fits into your parents’ overall financial health, see our guide on how to help your parents claim all their Merdeka Generation benefits without the confusion.

    Why the Merdeka Generation Should Prioritise LPA Now

    If your parents belong to the Merdeka Generation, they are likely in their late 60s to early 80s. This is the age when health conditions that affect mental capacity become more common. Dementia, for example, affects about 1 in 10 people aged 60 and above in Singapore. The risk increases with age.

    Many Merdeka Generation seniors also hold significant assets. They may own an HDB flat, have CPF savings, and receive monthly payouts from CPF LIFE. They may also be entitled to healthcare subsidies, CHAS benefits, and Medisave top-ups. Without an LPA, these assets and benefits become difficult to manage if they lose capacity.

    You might also want to explore should you top up your parents’ Medisave? What caregivers need to know to ensure their healthcare savings are sufficient.

    How LPA Connects to CPF and Estate Planning

    The LPA is just one piece of your parents’ overall planning. They also need a valid CPF nomination and a will.

    A CPF nomination tells the CPF Board who should receive their CPF savings after they pass away. Without a nomination, their CPF savings are distributed under the intestacy laws, which may not match their wishes.

    An LPA, however, is about managing their CPF while they are alive but lack capacity. For example, if your parent needs to pay for a nursing home but cannot sign the paperwork, the donee can use their CPF or bank account to make the payment.

    Learn more about what happens to your CPF when you pass away? A guide for families for the full picture.

    When Not Having an LPA Hurts the Whole Family

    Picture this scenario. Your father has dementia and needs to be moved to a nursing home. His only income is his CPF LIFE payout and a small pension. The nursing home fees are $2,500 per month. His CPF payout is only $1,200. He has $80,000 in his bank account. But without an LPA, you cannot touch that bank account. You cannot sell his HDB flat to raise funds either.

    You end up paying for his care out of your own pocket for months while you wait for the court to appoint you as deputy. This drains your own savings and causes tension with your spouse.

    This scenario is all too common. Do not let it happen to your family.

    Common Objections and How to Address Them

    Your parents might resist setting up an LPA. Here is how to respond to their concerns.

    “I am not old yet.” Age is not the only factor. An accident or illness can strike at any time. The LPA is a safety net, not a sign of decline.

    “I trust you to handle things.” Trust is not the issue. The law requires legal authority. Without the LPA, even a trusted child cannot act.

    “It is too expensive.” The registration fee is $50 or $75. Compare that to thousands of dollars in legal fees for a deputyship application.

    “I do not want to give up control.” The LPA only takes effect when your parents lose mental capacity. They remain in full control while they are capable.

    For more on avoiding pitfalls, check our article on 5 common mistakes Merdeka Generation seniors make when claiming healthcare subsidies. It covers related areas where families often slip up.

    A Practical Action Plan for Caregivers

    Here is your to-do list for the next 30 days.

    • Week 1: Talk to your parents about LPA. Share this article with them.
    • Week 2: Identify which sibling or family member should be the donee. Choose a replacement donee too.
    • Week 3: Download Form 2 from the Office of the Public Guardian website. Fill it in together with your parents.
    • Week 4: Book an appointment with a certificate issuer. Submit the form for registration.

    You can also combine the LPA conversation with a broader review of your parents’ benefits. Our guide on how to combine Merdeka Generation benefits with other government schemes for maximum savings can help you identify other areas where your parents may be missing out.

    Your Parents’ Future Depends on This Document

    Helping your parents set up a Lasting Power of Attorney is one of the most caring things you can do as a caregiver. It protects their finances, their healthcare choices, and their dignity. It also protects you from unnecessary stress, cost, and legal battles.

    Do not wait for a crisis. Start the conversation this week. Book the appointment. Get it done. Your future self and your parents will thank you.
  • 4 Senior-Friendly Neighbourhoods in Singapore Where Merdeka Generation Can Age Comfortably

    4 Senior-Friendly Neighbourhoods in Singapore Where Merdeka Generation Can Age Comfortably

    Choosing where to live after retirement is one of the biggest decisions you will make. For Merdeka Generation seniors, the right neighbourhood can mean the difference between feeling isolated and enjoying a vibrant, supported lifestyle. Singapore has done a lot to make many estates more age-friendly, but not all areas are equal. In this guide, we will walk you through the qualities of a senior friendly neighbourhood and highlight four places where Merdeka Generation seniors can truly age with comfort and peace.

    Key Takeaway

    Senior friendly neighbourhoods in Singapore share key features: flat walking paths, easy access to public transport (MRT/bus interchanges), nearby polyclinics and community hospitals, plenty of sheltered seating, and active ageing programmes. Four estates that excel in these areas are Bishan, Tiong Bahru, Toa Payoh, and Woodlands. Each offers unique advantages for Merdeka Generation seniors, from healthcare hubs to intergenerational community spaces. Use the table in this article to compare them against your own priorities.

    What Makes a Neighbourhood Truly Senior Friendly?

    Before we name specific estates, it helps to understand the checklist that defines a senior friendly neighbourhood. The Housing and Development Board (HDB), together with the Ministry of Health and LTA, has rolled out many improvements in recent years. Here are the key criteria you should look for:

    • Level walkways and ramps: No steep slopes or uneven pavements. Many HDB precincts now have covered linkways that connect blocks to bus stops and MRT stations.
    • Grab bars and rest points: Benches placed every few hundred metres, especially along park connectors and near market stalls.
    • Healthcare within 15 minutes: A polyclinic, a community hospital, or a CHAS GP clinic near home. This is where your Merdeka Generation outpatient subsidies really save you time and money.
    • Active ageing centres: Spaces like Senior Activity Centres (SACs) and Active Ageing Hubs that offer exercise classes, interest groups, and health screenings.
    • Good public transport connectivity: Being near an MRT station or a bus interchange means you can get around easily even if you stop driving.
    • Affordable daily essentials: Wet markets, NTUC FairPrice, Sheng Siong, and food centres that accept senior discounts and PAssion card perks.

    These elements matter because they reduce dependence on family members and let you maintain independence for longer.

    Four Standout Senior Friendly Neighbourhoods in Singapore

    Each of the four neighbourhoods below has been chosen for its combination of accessibility, healthcare access, community feel, and Merdeka Generation friendly amenities. They are not ranked in any particular order.

    1. Bishan: The Park Connector Paradise

    Bishan is a top pick for seniors who love greenery and staying active. The Bishan Ang Mo Kio Park is a huge draw, with flat walking paths that are easy on the knees. The neighbourhood has a wide variety of facilities:

    • Bishan MRT station on the Circle Line and the upcoming Cross Island Line connection makes it very connected.
    • Raffles Hospital Bishan branch and several CHAS clinics nearby.
    • Bishan Community Club runs many free active ageing programmes.
    • The Bishan Library is senior friendly, with large print collections and comfortable seating.

    For Merdeka Generation seniors, the proximity to Thompson Medical Centre and the Bishan Polyclinic means you can use your https://merdekageneration.sg/chas-card-benefits-explained-what-merdeka-generation-seniors-need-to-know/ without travelling far. Many residents also appreciate the Bishan Junction 8 shopping centre, which has senior discount days at selected retailers.

    2. Tiong Bahru: Heritage, Accessibility, and Community

    Tiong Bahru is one of Singapore's oldest housing estates, but it has been thoughtfully upgraded for ageing in place. Its pre war walk ups are balanced by newer HDB blocks with full barrier free access. What makes Tiong Bahru stand out:

    • Tiong Bahru Market is legendary for cheap and healthy hawker food. Many stallholders offer senior discounts during off peak hours.
    • Tiong Bahru Plaza and the neighbourhood shops are all within a short flat walk.
    • The Outram Park MRT interchange (East West Line, North East Line, and Thomson East Coast Line) is just a few minutes away.
    • Singapore General Hospital and Outram Community Hospital are located at the edge of the estate, giving you world class medical care a stone's throw away.
    • The Tiong Bahru Community Centre runs line dance, tai chi, and sketching classes tailored for seniors.

    For those who still drive, the estate has ample senior priority parking lots near the market. And if you ever need to claim your the nearby CHAS GP clinics are very experienced with Merdeka Generation claims.

    3. Toa Payoh: The Well Planned Heartland

    Toa Payoh was designed as a self contained satellite town, and its layout remains one of the most senior friendly in Singapore. The HDB town centre has wide covered walkways that connect almost every block to the bus interchange and MRT station.

    • Toa Payoh Polyclinic is a major healthcare hub that accepts Merdeka Generation subsidies for specialist referrals.
    • Toa Payoh Community Hospital is collocated with the polyclinic, making follow up visits easy.
    • The HDB Hub area includes a public library with large print books and a senior activity centre on level three.
    • Toa Payoh Central has sheltered seating areas with fans, perfect for morning coffee and catching up with neighbours.
    • The Safra Toa Payoh clubhouse hosts affordable fitness classes for seniors every weekday morning.

    If you are considering downsizing, Toa Payoh offers many 2 room Flexi flats designed for elderly residents, with features like emergency pull cords and slip resistant floors. You can learn more about the financial side of such a move in our guide on

    4. Woodlands: A Growing Hub for Active Ageing

    Woodlands in the north has evolved rapidly and now rivals more central estates in senior friendliness. The Woodlands Regional Centre includes a brand new integrated transport hub with direct undercover access to the MRT, bus interchange, and a shopping mall.

    • Woodlands Polyclinic is one of the largest in Singapore, with a dedicated seniors clinic that streamlines repeat prescriptions.
    • Admiralty Medical Centre and Khoo Teck Puat Hospital are a short bus ride away, offering comprehensive geriatric services.
    • The Woodlands Active Ageing Hub (Causeway Point area) runs free health talks, Zumba Gold, and gardening sessions.
    • Woodlands Galaxy Community Club has a special seniors corner with computers for digital literacy classes.
    • The Woodlands Waterfront Park has a completely flat promenade, ideal for walking or wheelchair use.

    Woodlands also has several wet markets and neighbourhood centres that accept the Merdeka Generation card for selected purchases. For seniors who need to claim several CHAS clinics in the area specialise in dental care for older adults.

    How to Evaluate a Neighbourhood: A Handy Comparison Table

    When you visit a potential neighbourhood, take this checklist with you. It covers the most important aspects from a Merdeka Generation perspective.

    Criteria What to Check Why It Matters for You
    Flat walking paths Are there slopes or steps? Is there a covered linkway from the nearest MRT to your block? Prevents falls and makes daily errands less tiring.
    Healthcare access How far is the nearest polyclinic or CHAS clinic? Does it accept MG subsidies? Reduces out of pocket costs and travel time for regular check ups.
    Food and groceries Is there a wet market or budget supermarket within 500 metres? Keeps your monthly expenses lower and supports a healthy diet.
    Community activities Are there Active Ageing Centres or senior interest groups nearby? Combats loneliness and keeps you engaged.
    Public transport Are there bus stops with benches? Is the MRT station barrier free? Ensures you can get around even if you no longer drive.
    Safety and lighting Are walkways well lit at night? Are there police posts or neighbourhood watch signs? Gives you peace of mind when returning home after dark.

    Take this table with you on your next visit to any of the four neighbourhoods. Tick off each row as you confirm it.

    Financial Tips for Moving to a Senior Friendly Neighbourhood

    Moving house later in life can feel daunting, especially with CPF and housing grants to think about. But Singapore has several schemes that make it easier for Merdeka Generation seniors to shift to a more suitable home.

    • Silver Housing Bonus: If you sell your current flat and buy a three room or smaller resale flat, you can get up to $30,000 in CPF top ups. This works well if you are downsizing from a larger flat in, say, Toa Payoh to a 2 room Flexi unit in the same town.
    • Lease Buyback Scheme: You keep living in your flat but sell part of the lease back to HDB for a stream of income. This is popular with seniors who want to stay put but need extra cash.
    • CPF top ups for housing: You can use your https://merdekageneration.sg/cpf-medisave-for-seniors-how-much-you-need-and-how-to-use-it-wisely/ to pay for renovation costs, like installing grab bars and ramps, under the Enhancement for Active Seniors (EASE) programme.

    Before you move, also check if your new neighbourhood has any grants for retrofitting. Many towns now offer free home improvement assessments for seniors over 60.

    "The best senior friendly neighbourhood is one that lets you age in place without sacrificing your social life. Look for an area where you can walk to the market, the clinic, and the community centre within 15 minutes. That keeps you independent longer." — Tan Bee Lian, senior social worker at a community hospital in Bishan.

    Making the Most of Your Merdeka Generation Benefits in These Neighbourhoods

    Living in a senior friendly neighbourhood is only half the picture. You also need to know how to use your Merdeka Generation Package benefits effectively. Each of the four neighbourhoods has specific resources that can help you stretch your dollar.

    • In Bishan, the Bishan Polyclinic has a dedicated MG counter that helps you claim your https://merdekageneration.sg/how-much-can-you-actually-save-on-polyclinic-visits-with-merdeka-generation-subsidies/ for each visit.
    • In Tiong Bahru, the SGH specialist outpatient clinic allows you to combine your MG subsidies with the https://merdekageneration.sg/does-your-specialist-visit-qualify-for-merdeka-generation-subsidies/ for lower bills.
    • Toa Payoh has several dental clinics that accept CHAS and MG subsidies. Check our https://merdekageneration.sg/6-dental-care-subsidies-merdeka-generation-seniors-can-tap-on-in-2026/ for eligibility.
    • Woodlands has a community health post at the bus interchange that offers free blood pressure checks and helps you enroll in the https://merdekageneration.sg/what-to-do-when-your-healthcare-subsidy-claim-gets-rejected/ if you ever face issues.

    If you are an adult child helping your parents, our guide on https://merdekageneration.sg/how-adult-children-can-help-parents-maximise-merdeka-generation-subsidies/ is a good starting point.

    Your Next Step Towards Comfortable Ageing

    Finding the right senior friendly neighbourhood takes some legwork, but it pays off every single day. Start by visiting one of the four estates we covered. Spend a morning walking around. Check if the walking paths are flat. Look for benches. Pop into a CHAS clinic and ask if they accept MG subsidies. Visit the community centre and see what programmes they run.

    If you are still unsure, write down your top three priorities. Is it healthcare access? Affordability of daily necessities? Or having plenty of green spaces? Match your priority against the strengths of each neighbourhood. You might find that Woodlands fits your love for parks, or that Tiong Bahru suits your need for convenience.

    Do not forget to talk to your family about your decision. They can help you with the paperwork for grants like the Silver Housing Bonus or the Lease Buyback Scheme. And always remember that your Merdeka Generation Package is designed to support you in these neighbourhoods, so use it to its full potential.

    Choosing a place to call home is a personal journey. But with the right information and a clear checklist, you can find a neighbourhood where you will feel safe, happy, and connected for many years to come.

  • How to Check Your CPF Statement Online: A Step-by-Step Guide for Seniors

    How to Check Your CPF Statement Online: A Step-by-Step Guide for Seniors

    Checking your CPF savings does not have to be complicated. Many seniors in Singapore think they need to visit a service centre just to see their balance. That is not true anymore. In 2026, you can check your CPF statement online from the comfort of your living room in your HDB flat. No queue. No paperwork. Just you, your smartphone or computer, and a few steps. This guide is written for Merdeka Generation seniors who are not very comfortable with technology. We will walk you through every click so you can stay on top of your retirement savings.

    Key Takeaway

    Checking your CPF statement online is a safe way to track your retirement savings, Medisave balance, and CPF LIFE payouts. You only need your Singpass and a device with internet. The entire process takes less than ten minutes. Once you learn it, you can check anytime you want without visiting a counter.

    Why You Should Learn to Check Your CPF Statement Online

    Your CPF money grows every year. The interest you earn on your Ordinary Account, Special Account, and Medisave Account adds up over time. If you only check your statement once a year by mail, you might miss out on opportunities to plan better. By checking online, you can see your balances instantly and make informed decisions about your retirement.

    For Merdeka Generation seniors, this is especially useful. You may have additional benefits like the Merdeka Generation Package top-ups that go into your account. Knowing your Medisave balance helps you plan for medical visits. Understanding your CPF LIFE payouts helps you budget your monthly expenses.

    What you can see in your CPF statement online:
    – Your total savings broken down by account
    – Monthly CPF LIFE payout details
    – Medisave contributions and withdrawals
    – Any top-ups or grants you received
    – Interest earned in the past year

    What You Need Before You Start

    Before you begin, gather these three things:

    1. Your Singpass credentials – This is your digital identity. If you have not activated Singpass yet, you can do it at any Singpass counter or ask a family member to help you set it up. You will need your IC number and a mobile number to receive One-Time Passwords.
    2. A device with internet – This can be a smartphone, tablet, laptop, or desktop computer. If you use a smartphone, a newer model makes the process smoother, but older models work too.
    3. A quiet place with good lighting – You will need to read small text, so sit near a window or under a bright lamp.

    If you do not have a smartphone or computer at home, you can use the computers at your nearest Community Club or public library. Staff there can guide you to the CPF website.

    Step-by-Step: How to Check Your CPF Statement Online

    Follow these steps carefully. If you get stuck at any point, do not worry. Just start over from step one.

    1. Open your browser and go to the CPF website. On your phone or computer, open the internet browser (the icon that looks like a globe or compass). Type in the address bar: www.cpf.gov.sg. Press enter.

    2. Click on the “Login” button. You will see it at the top right corner of the screen. It is usually a green button that says “Login with Singpass”.

    3. Enter your Singpass ID and password. This is the same ID you use for government services. If you have forgotten your password, click on the link that says “Forgot your password?” and follow the instructions. You may need your IC number to reset it.

    4. Complete the 2FA (Two-Factor Authentication). After entering your password, a code will be sent to your registered mobile phone via SMS. Type that code into the box on the screen. This step makes sure no one else can access your account.

    5. Click on “My Statement” on the dashboard. Once you are logged in, you will see a menu. Look for a section called “My Statement” or “View Statement”. Click on it.

    6. Select the statement period. The system will show you a list of past statements. Choose the most recent one (usually the latest month or quarter). Then click “View” or “Download”.

    7. Read your statement. The statement opens as a PDF file. You can scroll through it to see your balances. If you want to keep a copy for yourself, click the download button (a downward arrow icon) to save it on your device.

    Tip: If the PDF looks too small, use the zoom in function on your browser. On a computer, hold down the Ctrl key and press the plus (+) sign. On a smartphone, pinch two fingers apart on the screen.

    Common Mistakes Seniors Make and How to Avoid Them

    Even careful seniors can slip up. Here is a table of typical errors and the easy fixes.

    Mistake Why it happens How to avoid it
    Typing wrong Singpass ID Many seniors have multiple logins for different accounts. Write your Singpass ID on a piece of paper kept in a safe place. Do not store it on your phone in case it gets lost.
    Using an old browser Older browsers may not display the CPF website properly. Make sure your browser is updated. On a smartphone, use Chrome or Safari. On a computer, use the latest version of Chrome, Firefox, or Edge.
    Forgetting 2FA code The code expires in a few minutes. Keep your phone nearby. If the code expires, simply request a new one and try again.
    Clicking on fake links Scammers create lookalike websites to steal your login. Always type the CPF website address yourself. Do not click links from emails or SMS when logging in.
    Trying to print the entire statement Paper gets wasted and you might lose the PDF. Instead of printing, save the PDF to your device. You can also email it to yourself or to a family member for safekeeping.

    Tips to Stay Safe While Checking Your CPF Statement Online

    Safety is important. Here are simple habits to protect your CPF savings from scammers.

    • Never share your Singpass password with anyone, including family members. If you need help, let them watch you log in but do not let them type your password.
    • Log out after every session. Look for the “Logout” button at the top right of the screen. Close the browser tab after you log out.
    • Avoid using public Wi-Fi in coffee shops or libraries. Use your home Wi-Fi or mobile data instead.
    • Set up a strong password that is easy for you to remember but hard for others to guess. Use a mix of letters and numbers, like your favourite hawker centre name with a few numbers added.
    • If you receive a call or SMS saying there is a problem with your CPF account, do not respond. Call CPF directly using the number on their official website.

    Expert Advice: “The safest way to access your CPF statement is to bookmark the official CPF website on your browser. That way, you will never accidentally land on a fake page. Also, set a calendar reminder every three months to check your statement. Regular checking helps you spot any errors or missing top-ups early.” – Mdm Lee, former CPF officer and current volunteer at Silver Infocomm.

    What to Do If You Still Have Trouble

    Technology can feel overwhelming. You are not alone. If you cannot complete the steps above, try these options:

    • Ask a trusted family member for help. Your children or grandchildren are usually familiar with Singpass and CPF portals. They can guide you through the steps over the phone or in person.
    • Visit a Singpass counter. Go to any Singpass counter at a Community Club or library. Bring your IC. Staff there can help you reset your password and give you a quick lesson on logging in.
    • Call the CPF hotline. Dial 1800-227-1188 (toll-free). Tell the officer that you need help to check your CPF statement online. They can walk you through the steps while you are on the phone.
    • Use the CPF mobile app. If you have a smartphone, download the “CPF” app from the App Store or Google Play. The app has larger text and icons. The login process is the same as the website.

    For more details on related topics, you might find these articles helpful:

    Make Checking Your CPF a Simple Monthly Habit

    Once you have successfully checked your CPF statement online for the first time, it becomes much easier the next time. Think of it like learning to use an ATM. The first few tries feel awkward, but soon it becomes second nature.

    Consider making it a habit to check your statement every three months. You can tie it to a regular event, like after receiving your CPF contributions from work or after your birthday. Set a reminder on your phone or write it on a calendar. By staying informed, you can make sure every cent you have saved works hard for your retirement.

    You have worked your whole life building your CPF savings. Taking ten minutes to see your statement online is a small effort for peace of mind. Try it today. And if you need help, remember the CPF hotline and your family are always there for you.

  • How to Save on Chronic Disease Treatments Using Merdeka Generation Healthcare Subsidies

    How to Save on Chronic Disease Treatments Using Merdeka Generation Healthcare Subsidies

    Living with a chronic condition like diabetes, high blood pressure, or high cholesterol means regular doctor visits, medication, and monitoring. For Merdeka Generation seniors in Singapore, these ongoing costs can add up. The good news is that the Merdeka Generation Package offers substantial healthcare subsidies to help manage these expenses. Understanding how to use these benefits properly can save you hundreds of dollars each year.

    Key Takeaway

    Merdeka Generation healthcare subsidies for chronic diseases work through three main schemes: CHAS outpatient subsidies, MediSave for medication and tests, and MediShield Life for hospital stays. By combining these benefits and choosing the right clinics, you can reduce your annual out-of-pocket costs significantly. This guide explains exactly how to apply these subsidies at every step of your treatment journey.

    Understanding the Merdeka Generation Package and Chronic Disease Care

    The Merdeka Generation Package was introduced to recognise Singaporeans born between 1950 and 1959. If you are aged 65 to 74 in 2026, you likely qualify. The package provides extra support for healthcare, including chronic disease management.

    Chronic conditions require long term care. You may need monthly medication, regular blood tests, and specialist consultations. Without subsidies, these visits can cost between S$30 and S$80 per trip to a general practitioner. With the right Merdeka Generation healthcare subsidies for chronic disease, you can pay much less.

    The package works alongside other government schemes. It does not replace them. Instead, it adds another layer of savings on top of what you already receive. This is why many seniors find that their total healthcare bill drops noticeably after they learn to stack these benefits correctly.

    If you are unsure whether you qualify, you can check your eligibility through the government’s official portal. For a detailed walkthrough, read our guide on how to check if you qualify for the Merdeka Generation Package in 2026.

    Three Key Subsidies That Lower Your Chronic Disease Costs

    There are three main ways the Merdeka Generation Package helps with chronic disease treatments. Each one targets a different part of your healthcare journey.

    1. Community Health Assist Scheme (CHAS) Subsidies

    CHAS is the most direct way to save on outpatient visits. As a Merdeka Generation cardholder, you receive higher subsidies at CHAS clinics. This applies to common chronic conditions like diabetes, hypertension, and lipid disorders.

    At a CHAS clinic, a typical consultation for a chronic condition costs around S$20 to S$30 after subsidy. Without CHAS, the same visit could cost S$50 or more. If you visit the clinic monthly, that is a saving of S$240 to S$360 per year.

    You can also use CHAS at participating dental clinics. This is helpful if your chronic condition requires dental care, such as gum disease management for diabetic patients. For more details, see our article on CHAS card benefits for Merdeka Generation seniors.

    2. MediSave for Medication and Tests

    Your MediSave account can be used to pay for chronic disease medications and diagnostic tests. The Chronic Disease Management Programme (CDMP) allows you to withdraw up to S$500 per year per account for outpatient treatment of selected chronic conditions.

    This is useful because it lets you use your own savings rather than cash. Many seniors do not realise that CDMP covers over 20 chronic conditions, including asthma, stroke, and arthritis. You can use MediSave at participating clinics and polyclinics.

    To make the most of this, always ask your doctor if your condition is covered under CDMP. If it is, you can use MediSave for part of the bill. This leaves more cash in your pocket for other expenses. Learn more about using MediSave wisely for seniors.

    3. MediShield Life Coverage for Hospital Stays

    If your chronic condition leads to hospitalisation, MediShield Life provides basic coverage. The Merdeka Generation Package includes additional premium subsidies for MediShield Life. This means you pay less for your insurance premiums while still getting the same coverage.

    For seniors aged 65 to 74, the premium subsidy can be significant. It reduces the amount you need to pay using MediSave or cash. This keeps your insurance active so you are protected if a chronic condition worsens.

    Read our full guide on maximising your MediShield Life coverage as a Merdeka Generation senior for more details.

    How to Use Your Merdeka Generation Benefits at the Clinic

    Visiting a clinic does not have to be confusing. Follow these steps to ensure you receive all the Merdeka Generation healthcare subsidies for chronic disease that you are entitled to.

    • Bring your Merdeka Generation card or your CHAS card to every appointment. The clinic needs to see it to apply the subsidy.
    • Tell the receptionist you are a Merdeka Generation patient. Some clinics have different workflows for different schemes.
    • Ask if your condition is covered under CDMP. If it is, request to use MediSave for the eligible portion.
    • Check your bill before paying. The subsidy should appear as a discount line item. If it is missing, ask the counter staff to check.
    • Keep your receipts. They help you track your annual MediSave usage and confirm that subsidies were applied.
    • Visit CHAS clinics in your neighbourhood. They are listed on the official CHAS website and most accept walk ins.

    By following these steps, you ensure that every visit saves you money. For a more complete overview, check our guide on how to use your Merdeka Generation card at clinics and hospitals.

    A Simple Comparison of Chronic Disease Subsidies

    The table below shows how the three main schemes compare for a typical chronic disease patient.

    Scheme What It Covers Typical Savings per Visit How to Claim
    CHAS (Merdeka Generation) Outpatient consultation and medication at CHAS clinics S$20 to S$40 Show your CHAS card at the clinic
    MediSave (CDMP) Medication and diagnostic tests for selected chronic conditions Up to S$500 per year Ask the clinic to submit a MediSave claim
    MediShield Life Hospital stay and selected outpatient treatments Premium subsidy of up to S$200 per year Automatically applied to your premium

    This table helps you see the full picture. Combining all three gives you the best protection. You save on daily visits, medication costs, and insurance premiums all at once.

    If you want to compare benefits with the Pioneer Generation, read our guide on Merdeka Generation vs Pioneer Generation benefits.

    Common Mistakes to Avoid When Claiming

    Even with generous subsidies, some seniors miss out because of simple errors. Here are the most common ones.

    “Many Merdeka Generation seniors assume their subsidies are applied automatically. In practice, you often need to present your card and ask specifically for CDMP coverage. A quick question at the counter can save you S$20 or more per visit.” – Healthcare advisor at a CHAS clinic

    • Forgetting to bring your card. Without your Merdeka Generation or CHAS card, the clinic cannot verify your eligibility. Keep it in your wallet at all times.
    • Not asking about CDMP coverage. Some clinics do not proactively offer it. Always ask if your medication is eligible for MediSave.
    • Visiting a non CHAS clinic. CHAS subsidies only apply at CHAS participating clinics. Non CHAS clinics do not accept the card.
    • Assuming all chronic conditions are covered equally. Each scheme has a list of approved conditions. Check the official list to avoid surprises.
    • Missing the annual MediSave limit. You can use up to S$500 per year under CDMP. Track your usage so you do not leave unused savings on the table.

    For a full list of pitfalls, read our article on 5 common mistakes Merdeka Generation seniors make when claiming healthcare subsidies.

    Your Next Steps for Lower Chronic Disease Costs

    You now know how the Merdeka Generation healthcare subsidies for chronic disease work. The next step is to put this knowledge into action.

    Start by checking your eligibility if you have not done so. Then locate your nearest CHAS clinic and schedule a visit. Bring your card and ask about CDMP coverage. Track your savings over the next few months. You will likely see a real difference in your out-of-pocket expenses.

    If you need help with a rejected claim or want to learn about additional subsidies, read our guide on what to do when your healthcare subsidy claim gets rejected and our article on applying for additional healthcare subsidies beyond the Merdeka Generation Package.

    Managing a chronic condition is not easy. But with the right subsidies, you can focus on your health without worrying about the cost. Use this guide as your starting point. Share it with your family so they can help you claim every benefit you deserve.

  • How to Retrofit Your HDB Flat for Safe and Comfortable Aging in Place

    How to Retrofit Your HDB Flat for Safe and Comfortable Aging in Place

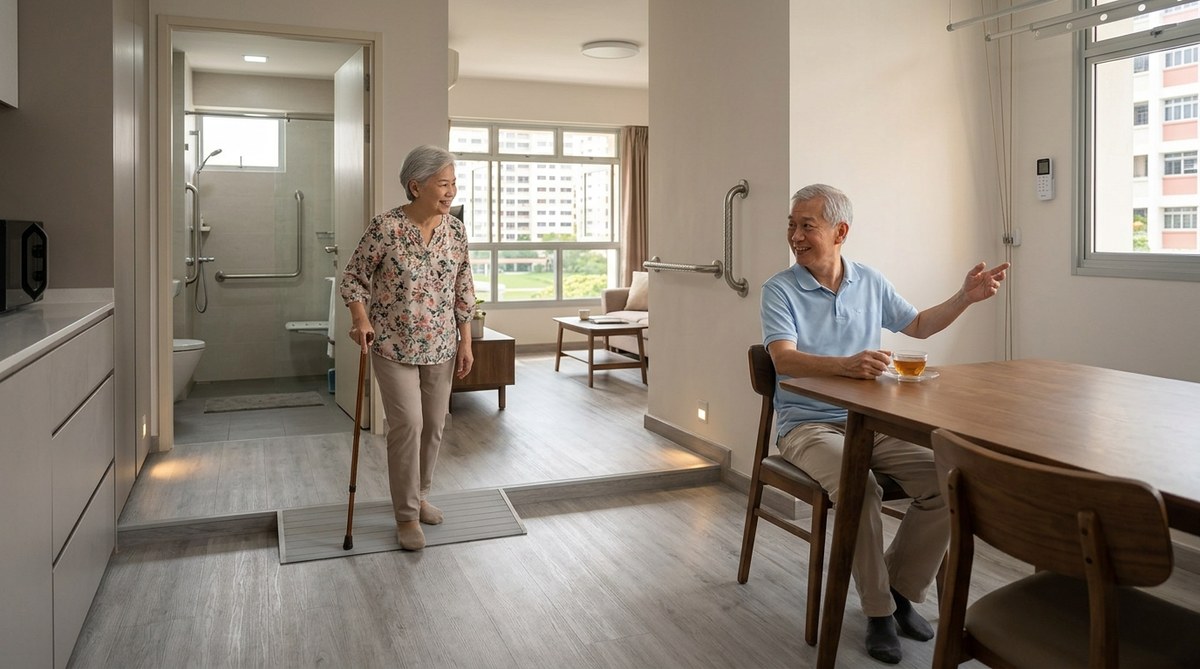
    Your HDB flat has been your home for decades. The children grew up here, you celebrated many CNY dinners in the living room, and the neighbourhood kopitiam knows your regular order. But as you or your parents get older, that same flat can start to feel less safe. The step into the shower feels higher. The corridor to the kitchen seems narrower. The thought of a fall becomes a real worry. The good news is you do not need to move out. With some smart modifications, your existing home can support you safely through the years ahead.

    Key Takeaway

    Retrofitting an HDB flat for aging in place does not have to be expensive or disruptive. Focus on a few high-impact areas: the bathroom, the entrance, and flooring. The Enhancement for Active Seniors (EASE) programme can subsidise up to 95% of costs for eligible households. Plan ahead based on current and future mobility needs, and always engage an HDB-approved contractor to ensure safety and compliance.

    Why Consider an HDB Aging in Place Retrofit

    Aging in place means living in your own home safely, independently, and comfortably, regardless of age or mobility level. For many Singaporean seniors, the Merdeka Generation, moving to a nursing home or a relative’s flat is not appealing. You know your neighbours. You know which lift lobby has the best breeze. Staying put preserves your social connections and your sense of independence.

    Beyond emotional comfort, practical reasons matter. The cost of retrofitting is often far lower than selling and buying a smaller flat or moving into a senior-friendly development. With government support through the your out-of-pocket expenses can be minimal. A retrofit can prevent falls, which are the leading cause of hospitalisation among seniors in Singapore. A safer home means fewer trips to the A&E and more peace of mind for everyone.

    Step 1: Assess Your Current and Future Needs

    Before buying grab bars or removing bathtubs, take stock. Start with a walkthrough of your flat with a critical eye. Better yet, ask a family member or an occupational therapist to help. They spot hazards you might overlook because you are used to them.

    Checklist for a Home Safety Audit

    • Are there any loose rugs or uneven floor tiles that could trip someone?
    • Can you stand and move freely in the bathroom, especially near the toilet and shower?
    • Do doorways allow a walker or wheelchair to pass through comfortably?
    • Is the lighting adequate, especially at night, from bedroom to toilet?
    • Are kitchen counters at a height that avoids excessive bending or reaching?
    • Do you have a step to enter the shower area?

    Use this audit to create a priority list. For example, if the bathroom floor gets slippery when wet, that becomes a high priority. If the kitchen counter height is fine now but may become an issue in five years, you can plan a medium-term fix.

    Step 2: Understand Available Grants and Schemes

    Singapore’s government has several schemes to help seniors retrofit their HDB flats. The most important is the Enhancement for Active Seniors (EASE) programme. HDB offers this subsidy for a fixed set of modifications. Eligible households can receive up to 95% subsidy, depending on income.

    Key Grants at a Glance

    Grant / Scheme What It Covers Subsidy Level Eligibility
    EASE (HDB) Grab bars, slip-resistant flooring, ramps, widening of doorways Up to 95% for lower-income; 87.5% for others Singapore citizen, HDB flat, at least one occupant aged 65+ or 60+ with mobility needs
    Seniors’ Mobility and Enabling Fund (SMF) Assistive devices like walking frames, wheelchairs, commodes Up to 90% subsidy, capped at amounts Singapore citizen, means-tested, referred by healthcare professional
    Ageing-in-Place Programme (AIP) Comprehensive retrofitting beyond EASE (e.g., kitchen, full bathroom remodel) Variable grants depending on flat type and income Must be EASE-eligible and living in selected HDB estates

    “We often tell families to start with the bathroom because that is where most falls happen. Even simple changes like a raised toilet seat and a grab bar can prevent a hip fracture.” – Occupational therapist from a Singapore public hospital

    Do not forget the Merdeka Generation seniors may qualify for additional healthcare subsidies that can cover the cost of consultations or therapy that inform your retrofit plans.

    Step 3: Choose High-Impact Modifications

    You do not need to overhaul the entire flat. Focus on the areas that pose the highest risk. Here is a numbered list of the most effective modifications, ranked by impact on safety.

    1. Install grab bars in the bathroom. Place them near the toilet and inside the shower. Steel or stainless steel grab bars that can support at least 200 kg are ideal. Make sure they are anchored into wall studs or installed with heavy-duty fixings.
    2. Replace slippery flooring. In bathrooms and kitchen, use slip-resistant tiles. For the rest of the flat, avoid high-pile carpets. Flat, non-slip vinyl or laminate is a good choice. Remove any loose rugs.
    3. Widen doorways. Standard HDB doorways can be too narrow for a wheelchair or walker. Widening them to at least 760 mm (about 30 inches) makes a big difference. This can be done during EASE renovations.
    4. Improve lighting. Add night lights along the path from bedroom to toilet. Use motion-sensor lights so you do not have to fumble for a switch. Brighten dark hallways with LED strips.
    5. Create a level entry. If you have a step at the main door or into the bathroom, install a small ramp or reduce the step height. Even a 2 cm difference can be a trip hazard.
    6. Raise toilet seats. A higher toilet seat (about 400–430 mm) reduces the effort to sit down and stand up. Many affordable add-on seats are available.
    7. Add a shower commode chair or fold-down seat. This allows showering while seated, greatly reducing fall risk.

    Step 4: Find a Trusted Contractor

    HDB has a list of approved contractors for EASE works. Stick to them. They understand HDB structural requirements and guarantee workmanship. If you need additional retrofitting beyond EASE (for example, a full kitchen redesign), look for contractors experienced with universal design. Ask for references or photos of past projects.

    What to Ask a Contractor

    • Are you familiar with HDB guidelines for elderly safety modifications?
    • Can you provide a detailed quotation including all materials and labour?
    • Do you help with grant applications or provide the necessary documentation?
    • How long will the work take? What measures do you take to minimise dust and disruption?

    Step 5: Create a Timeline and Budget

    Some retrofitting can happen over a weekend. Other jobs require coordination with neighbours, especially if there is noisy renovation work. Plan around major holidays or family events.

    Sample Budget for a Basic EASE Retrofit

    Modification Estimated Cost before Grant After 87.5% Subsidy (For Homeowner above PCHI threshold)
    Grab bars (set of 3) $400 $50
    Slip-resistant flooring in bathroom & toilet $600 $75
    Ramps for main entrance and bathroom $300 $37.50
    Widening of one doorway $500 $62.50
    Total $1,800 $225

    Numbers are rough estimates and change yearly. Check the https://merdekageneration.sg/scheme-updates-guide/ for current figures.

    Common Mistakes to Avoid

    Even with good intentions, people make errors. Here are pitfalls to watch for, and how to steer clear.

    Mistake Why It Is a Problem Better Approach
    Installing grab bars in wrong location They end up too far to reach or mounted on hollow wallboard Have an occupational therapist mark positions before drilling
    Choosing cheap non-slip mats They can curl up at edges, causing trips Invest in fixed slip-resistant floor tiles or sheets
    Forgetting about lighting Dim corridors remain hazardous even with grab bars Install automatic night lights along the main path
    Overdoing changes too soon Unnecessary expense may reduce resale appeal or aesthetics Prioritise high-risk areas first; leave cosmetic upgrades for later

    Making Your Retrofit Sustainable

    A good retrofit does not just solve today’s problems. It also adapts to future needs. For example, if you install grab bars now, leave space so that a caregiver can assist later. Choose lever handles instead of round doorknobs; they are easier for arthritic hands. Consider a built-in shelf in the shower for toiletries at a reachable height.

    Remember that aging in place is not only about physical safety. It involves social and financial well-being too. The https://merdekageneration.sg/top-senior-friendly-housing-options-in-singapore-for-comfortable-aging/ article explores other housing choices if retrofitting is not enough.

    Final Steps: Putting the Plan into Action

    You now have a clear roadmap. Let us summarise the steps:

    • Perform a home safety audit with a family member or professional.
    • Check your eligibility for EASE and other subsidies.
    • Decide on two or three high-impact modifications to start.
    • Book an approved contractor through HDB.
    • Arrange the work timeline to minimise disruption.
    • Test the changes and adjust as needed.

    A single fall in the bathroom can change your life. A simple grab bar and a night light can prevent that fall. Do not wait until an accident happens. Start planning your retrofit this year.

    If you are also managing other aspects of retirement finances, read our guide on https://merdekageneration.sg/should-you-downsize-your-hdb-flat-for-extra-retirement-cash/ for a broader view of housing choices. And if you need healthcare subsidy support, the https://merdekageneration.sg/how-much-can-you-actually-save-on-polyclinic-visits-with-merdeka-generation-subsidies/ article can help you save more.

    Your home should be your sanctuary, not a hazard. With the right modifications, you can enjoy many more years of comfort, independence, and safety in the flat you love.

  • How to Optimize Your CPF Contributions for Better Retirement Benefits in 2026

    How to Optimize Your CPF Contributions for Better Retirement Benefits in 2026

    Optimising your Central Provident Fund (CPF) contributions in 2026 is more crucial than ever for Singaporeans planning a comfortable retirement. With upcoming changes and new schemes, understanding how to make the most of your CPF can significantly impact your financial security. Whether you are in your 30s or 50s, knowing the right steps now can set you up for a more relaxed future. Let’s look at the latest tips and strategies to help you navigate CPF contributions in 2026 effectively.

    Key Takeaway

    Maximising your CPF contributions in 2026 involves understanding new contribution limits, taking advantage of special schemes like the Merdeka Generation Package, and planning your deposits strategically. Starting early and making informed choices can boost your retirement savings, ensuring a comfortable future in Singapore’s evolving landscape.

    Understanding the 2026 CPF Landscape and Key Changes

    Singapore’s CPF system is designed to help citizens save for retirement, housing, and healthcare. Every year, the government adjusts contribution rates, caps, and schemes to adapt to economic changes and demographic shifts. In 2026, several notable updates can influence how you plan your CPF contributions.

    New Contribution Limits and Rates

    One of the biggest updates in 2026 is the rise in the CPF wage ceiling, which now caps contributions at S$8,000 monthly. This means higher earners can contribute more towards their CPF accounts, boosting their retirement nest egg. Contribution rates for those aged 55 to 65 are also increasing, encouraging older workers to save more as they approach retirement.

    The Merdeka Generation Package and Benefits

    The Merdeka Generation Package remains a key scheme for eligible seniors. It offers subsidies, healthcare benefits, and top-ups that can complement your CPF savings. If you qualify, combining your CPF contributions with these benefits can enhance your overall retirement plan.

    Healthcare and Medisave Adjustments

    In 2026, the Medisave cap rises to S$79,000, allowing you to save more for healthcare needs. This is especially important as healthcare costs in Singapore continue to climb. Making regular contributions to your Medisave account ensures you are prepared for medical expenses without dipping into your retirement funds.

    Practical Steps to Optimise Your CPF Contributions in 2026

    Maximising your CPF savings involves a combination of understanding the new rules and adopting a disciplined approach. Here are three practical steps to help you get started:

    1. Review and Adjust Your Monthly Contributions

    2. Check your current wages and contribution rates.

    3. Increase your contribution percentage if you are earning above the new wage ceiling.
    4. Consider voluntary top-ups to your CPF accounts, especially to the Special Account, which earns higher interest rates.

    5. Leverage Government Schemes and Top-Ups

    6. Take advantage of the Merdeka Generation Package if eligible.

    7. Use the tax relief for voluntary contributions to boost your savings while enjoying tax benefits.
    8. Consider topping up your Medisave account for healthcare security.

    9. Plan Your Contributions Based on Your Retirement Goals

    10. Use tools like CPF’s retirement calculators to estimate how much you need.

    11. Set a target contribution amount each year to meet your desired retirement sum.
    12. Review your progress annually and adjust contributions as your income or circumstances change.

    Bonus Tips for Enhanced CPF Contribution Strategies

    • Automate your contributions to stay consistent.
    • Take advantage of special interest rates on the Retirement Account.
    • Combine CPF savings with other investment options to diversify your retirement portfolio.

    Common Pitfalls and How to Avoid Them

    While boosting your CPF contributions is beneficial, there are some common mistakes to watch out for:

    Technique Mistake How to Avoid It
    Increasing voluntary top-ups Over-contributing beyond tax relief limits Stay within the annual cap for tax relief, usually S$7,000 for CPF top-ups
    Ignoring contribution caps Failing to adjust for the new wage ceiling Review your wages and contribution rates regularly
    Neglecting healthcare contributions Not topping up Medisave Allocate part of your savings for Medisave — it’s vital for healthcare needs

    “Maximising CPF contributions requires discipline and strategic planning. Regularly review your income and adjust your deposits to stay ahead of upcoming changes,” advises financial expert Mr Lee.

    Mistakes to Watch Out For

    • Contributing less than the mandatory minimum to benefit from compound interest.
    • Failing to utilise tax relief options through voluntary top-ups.
    • Overlooking the importance of Medisave contributions for healthcare security.

    How to Make the Most of CPF Contributions in 2026

    Here are actionable tips to ensure your CPF contributions work harder for your retirement:

    1. Start Early
      The power of compound interest means the earlier you begin, the more your savings grow. Even small increases in your monthly contributions can lead to significant gains over time.

    2. Increase Contributions During Salary Raises
      When you receive a salary bump, consider increasing your CPF contributions proportionally. This helps build your nest egg faster.

    3. Use Voluntary Top-Ups Strategically
      Making lump-sum top-ups not only boosts your savings but also grants you tax relief. Focus on topping up your Special Account for higher interest earnings.

    4. Utilise the Merdeka Generation Benefits
      If eligible, combine your CPF savings with the Merdeka Generation Package benefits to maximise healthcare subsidies and other support.

    5. Review and Adjust Annually
      As your income or circumstances change, revisit your contribution plan. Stay informed about policy updates through official channels like the CPF website.

    6. Consult Financial Advisors or Use Planning Tools
      Use available CPF calculators or seek advice to tailor your contribution strategy based on your retirement age, lifestyle, and health needs.

    Common Mistakes in CPF Contributions and How to Correct Them

    Mistake Impact How to Fix It
    Contributing below the mandatory rate Lower interest earnings Increase contributions to at least the minimum required
    Not taking advantage of tax relief Missed savings Make voluntary top-ups before year-end to enjoy tax benefits
    Over-contributing Penalties or wasted funds Monitor contribution caps and adjust accordingly
    Ignoring healthcare needs Insufficient Medisave Regularly top up your Medisave account to cover future healthcare costs

    “A well-planned CPF contribution strategy in 2026 can give you a head start. Balance your savings with healthcare needs and tax benefits to enjoy peace of mind,” says financial planner Ms Tan.

    Your Retirement Planning in a Changing Singapore

    Optimising your CPF contributions in 2026 is about more than just saving. It’s about making informed decisions that align with your long-term goals. The upcoming changes present opportunities to boost your retirement funds, provided you approach them strategically. Remember, starting early and staying consistent can make a significant difference.

    Don’t forget to review your CPF statements regularly and stay updated on new schemes or adjustments. Combining CPF savings with other investment options can further secure your future, giving you the freedom to enjoy your retirement years comfortably.

    Taking Control of Your Retirement Savings Today

    Your future self will thank you for the effort you put into maximising your CPF contributions now. Use the upcoming changes in 2026 as a catalyst to review, plan, and execute your retirement strategy. With careful planning and disciplined savings, you can build a financial cushion that supports your lifestyle in Singapore’s vibrant, dynamic environment. Start today, and take confident steps toward a secure retirement in the years ahead.

  • How to Plan Your CPF Withdrawals for a Stress-Free Retirement in 2026

    How to Plan Your CPF Withdrawals for a Stress-Free Retirement in 2026

    Retirement planning can feel overwhelming, especially with the upcoming changes in 2026 that impact CPF withdrawal rules. Many pre-retirees in Singapore are now looking for clear guidance on how to optimise their CPF savings and make withdrawals that support a comfortable, stress-free retirement. With the government introducing schemes like the Merdeka Generation Package and adjustments to CPF policies, understanding your options is more important than ever.

    Key Takeaway

    Effective CPF withdrawal planning in 2026 involves understanding new rules, leveraging benefits like the Merdeka Generation Package, and adopting practical strategies to maximise your retirement funds. Start early and stay informed to enjoy a worry-free retirement in Singapore.

    Understanding the 2026 Changes to CPF Withdrawal Rules

    In 2026, Singapore will implement important updates to CPF withdrawal policies. These changes aim to streamline retirement payouts, encourage better planning, and ensure seniors have sufficient funds in their retirement years. For example, the government will introduce adjustments to the CPF Retirement Sum scheme, affecting how much you can withdraw at age 55 and beyond.

    Moreover, the Merdeka Generation Package, which many eligible seniors benefit from, will continue to offer subsidies and healthcare support. Knowing if you qualify and how to integrate these benefits into your withdrawal plans can make a significant difference in your financial security.

    Step-by-Step Approach to CPF Withdrawal Planning in 2026

    Preparing for your retirement in 2026 requires a systematic approach. Here’s a simple process to help you get started:

    1. Assess your current CPF savings and projected needs
      Take stock of your CPF balances, including Ordinary Account, Special Account, and Retirement Account. Use the CPF online services to review your statements and understand how much you can potentially withdraw or allocate for future needs.

    2. Identify your retirement goals and income sources
      Determine the lifestyle you want in retirement. Will you travel, downsize your home, or need additional healthcare support? Consider other income streams like CPF LIFE payouts, pensions, or personal savings to see how they complement your CPF funds.

    3. Align your withdrawal strategy with upcoming policies
      Understand the new rules for CPF withdrawal in 2026. For instance, the mandatory withdrawal age may be adjusted, or the amount you can withdraw at 55 might change depending on your CPF balances and the new scheme thresholds. Plan your withdrawals accordingly to avoid unnecessary penalties or shortfalls.

    Practical Tips for Optimising Your CPF Withdrawals in 2026

    • Start early
      The sooner you review your CPF accounts and retirement plans, the better. Early planning gives you time to adjust your contributions or savings to meet your desired retirement lifestyle.

    • Leverage government schemes
      If you qualify for the Merdeka Generation Package, take full advantage of subsidies and healthcare benefits to reduce out-of-pocket expenses. These savings can be redirected into your CPF or savings account for future use.

    • Consider CPF LIFE plans
      Choosing the right CPF LIFE payout plan can ensure a steady income stream. You might opt for the Standard, Escalating, or Customised plans based on your expected expenses and risk appetite.

    • Utilise CPF withdrawal limits wisely
      Be aware of the withdrawal limits set by the government. Over-withdrawing can leave you with insufficient funds later, while under-withdrawing may not meet your immediate needs.

    • Plan for healthcare costs
      Healthcare expenses tend to rise with age. Maximise your MediSave and Medishield Life coverage, and consider supplementing these with private healthcare plans if necessary.

    • Avoid common mistakes
      Poor planning can lead to unforeseen financial stress. For example, withdrawing too much early on, not considering inflation, or neglecting estate planning can impact your retirement quality.

    A Closer Look at Retirement Income and Withdrawal Techniques

    Technique Description Common Mistake Benefit
    Lump-sum withdrawal Taking a full sum at retirement Overestimating immediate needs Provides cash for large expenses or investments
    Phased withdrawal Regular, smaller withdrawals Not adjusting for inflation Ensures steady income and longevity planning
    Combining CPF LIFE with savings Using both for flexibility Ignoring healthcare costs Balances income and health expenses

    “The key to stress-free retirement is planning ahead and understanding your options thoroughly,” advises financial expert Mr Lim Wei. “With the right strategies, you can enjoy your golden years without financial worries.”

    Common Pitfalls to Watch Out for in 2026

    • Ignoring new withdrawal limits
      Failing to adapt your plans to the updated rules can result in unnecessary penalties or missed opportunities.

    • Neglecting healthcare expenses
      Overlooking rising medical costs can deplete your CPF or savings faster than expected.

    • Not updating estate nominations
      Ensure your CPF nominations and estate plans reflect your current wishes to avoid complications later.

    • Underestimating inflation
      Remember that the cost of living in Singapore continues to rise. Factor this into your withdrawal and investment plans.

    Make Your Retirement Dreams a Reality

    As Singapore’s retirement landscape evolves, so should your financial strategies. By understanding the changes in CPF withdrawal policies for 2026, leveraging government benefits like the Merdeka Generation Package, and adopting disciplined planning, you can create a retirement that is both enjoyable and secure.

    Start reviewing your CPF balances today, set clear financial goals, and stay updated on policy changes. With thoughtful preparation, your retirement years can be filled with peace of mind, good health, and the freedom to enjoy what truly matters.

    Retiring in Confidence: Your Next Steps

    Take control of your future by making informed decisions now. Attend retirement planning seminars, consult with financial advisors familiar with CPF policies, and regularly review your plans as policies evolve. Remember, early and consistent planning makes all the difference.

    Wishing you a fulfilling retirement journey in 2026 and beyond!

  • Smart Strategies to Maximise Your CPF Retirement Funds in 2026

    Smart Strategies to Maximise Your CPF Retirement Funds in 2026

    Maximising your CPF retirement funds in 2026 is a smart move for Singaporeans aged 30 to 50 who want a comfortable retirement. With the evolving schemes and benefits introduced by the government, understanding how to optimise your CPF savings now can make a big difference later. Whether you are just starting or looking to fine-tune your current plan, knowing the latest strategies can help you secure a more stable financial future.

    Key Takeaway

    To maximise your CPF retirement funds in 2026, focus on strategic contributions, utilise government schemes like the Merdeka Generation Package, and consider investments that enhance your savings growth. Planning early ensures higher payouts and financial security for your golden years.

    Understanding the Latest CPF Changes in 2026

    Singapore’s CPF system continues to evolve, offering more avenues for members to grow their savings. In 2026, the government rolled out several updates aimed at helping working adults boost their retirement nest egg. These include enhanced interest rates on Special Account (SA) and Retirement Account (RA), new schemes for voluntary top-ups, and increased flexibility in how members can manage their funds.

    Knowing these changes is essential. They provide opportunities to increase your CPF balances through legitimate means, especially with schemes designed for your age group. The key is to stay informed about these updates and leverage them for maximum benefit.

    Practical Steps to Boost Your CPF Savings

    To make the most of your CPF funds in 2026, follow these proven steps:

    1. Maximise your voluntary contributions
    2. Top up your CPF accounts, especially your Special Account (SA) and Retirement Account (RA).
    3. Take advantage of the tax relief benefits, which can reduce your taxable income while increasing your savings.
    4. Consider using the [MediSave Top-Up shield-life-coverage-as-a-merdeka-generation-senior) to ensure adequate Medisave for healthcare costs.

    5. Utilise government schemes like the Merdeka Generation Package

    6. Check your eligibility for the Merdeka Generation Package, which offers subsidies and cash benefits that indirectly save your cash flow.
    7. The package includes additional healthcare subsidies and dental benefits that help reduce out-of-pocket expenses, freeing up cash for CPF contributions or investments.
    8. Visit the Merdeka Generation Package page to confirm your status.

    9. Invest your CPF savings strategically

    10. Consider CPF Investment Schemes (CPFIS) to grow your balances beyond the guaranteed interest rates.
    11. Focus on low-risk, stable investments that complement your retirement timeline.
    12. Always diversify to avoid putting all your eggs in one basket and review your portfolio regularly.
    Technique Mistake to Avoid
    Making only the minimum CPF contributions Underfunding your retirement savings
    Ignoring investment opportunities within CPF Relying solely on guaranteed interest rates
    Not planning for healthcare costs Overlooking possible medical expenses in later years

    Expert tip: “Start early and contribute consistently. Even small top-ups compound significantly over time, especially with the current attractive interest rates and government incentives.” — Financial advisor in Singapore

    Smart Strategies to Increase Your Payouts in Retirement

    Maximising your CPF funds is not just about growing the balance but also about increasing your payouts in retirement. Here are some tactics:

    • Defer your CPF LIFE payouts if you are in good health. This can lead to higher monthly payouts later, giving you more financial flexibility.
    • Opt for the escalating plan if you prefer your payouts to increase over time, helping offset inflation.
    • Transfer funds from OA to SA or RA when possible. The higher interest rates on SA and RA help your savings grow faster, boosting future payouts.

    Common pitfalls to avoid

    Technique Mistake to Avoid
    Withdrawing CPF savings prematurely Reduces your retirement corpus
    Ignoring inflation impact Payouts not keeping pace with rising costs
    Not reviewing payout plans Missing opportunities to optimise payouts

    How to Fine-Tune Your Retirement Plan in 2026

    A well-designed plan involves balancing contributions, investments, and payout strategies. Here’s how to review yours:

    • Regularly check your CPF statements and dashboards to track growth and identify gaps.
    • Take advantage of the Silver Housing Bonus and Lease Buyback Scheme if you own property. These schemes can free up cash or provide additional income streams.
    • Plan for healthcare costs by topping up MediSave and exploring subsidies like the CHAS card benefits.

    Mistakes to steer clear of:

    Mistake Consequence
    Overlooking healthcare planning Unexpected medical expenses strain finances
    Ignoring inflation adjustments Payouts become less sufficient over time
    Failing to review estate plans Assets may not be allocated as desired

    How to Maximise Your CPF Benefits in 2026

    Maximising your CPF is a multi-layered process. Here are key techniques:

    • Make regular voluntary contributions, especially during bonus seasons or when you receive windfalls.
    • Use government schemes to top up your accounts, which can also unlock additional benefits or subsidies.
    • Invest prudently through the CPFIS to grow your savings faster.
    • Keep abreast of policy updates that may introduce new benefits or schemes.
    Technique Mistake to Avoid
    Relying solely on CPF contributions Missing out on investment growth
    Not updating your nomination Assets not allocated as you intend
    Ignoring healthcare benefits Higher medical costs in later years

    Expert quote:

    “The earlier you start, the more you can leverage the power of compounding. Combining this with government schemes ensures your retirement funds grow effectively,” advises a senior financial planner.

    Making the Most of Government Benefits and Schemes

    The government offers several schemes for Singaporeans in the Merdeka Generation and beyond. These include healthcare subsidies, top-up schemes, and housing benefits that indirectly boost your retirement readiness.

    • Merdeka Generation Package: Offers healthcare subsidies, special benefits, and cash top-ups.
    • Silver Housing Bonus: Provides extra cash when downsizing or selling your property.
    • CPF Top-Up schemes: Allow you to boost your retirement savings while enjoying tax relief.

    Always verify your eligibility for these schemes. Proper utilisation can significantly increase the resources available for your retirement.

    A Final Word on Retirement Readiness in 2026

    Maximising your CPF retirement funds involves consistent effort, strategic planning, and staying updated on policy changes. Start today by assessing your current savings, exploring government benefits, and considering investment options suited to your risk appetite. Remember, the goal is to build a resilient financial foundation that supports your lifestyle and healthcare needs well into your golden years.

    By taking action now, you set yourself up for a worry-free retirement. Use the opportunities available, keep your plans flexible, and regularly review your progress. Retirement in Singapore can be a rewarding phase when you actively manage your CPF funds and benefits.


    Stay proactive in your planning, and let your CPF savings work harder for you in 2026 and beyond.

  • Maximising Healthcare Subsidies for Your Retirement Years in Singapore

    Maximising Healthcare Subsidies for Your Retirement Years in Singapore

    Retiring in Singapore offers a comfortable lifestyle, but healthcare costs can quickly add up without proper planning. Fortunately, the government provides several schemes and subsidies designed specifically for seniors, especially Merdeka Generation seniors. Knowing how to maximise these benefits can make a significant difference in your retirement budget. In 2026, staying informed and proactive will help you enjoy your golden years with peace of mind and financial security.

    Key Takeaway

    Maximising healthcare subsidies involves understanding your eligibility, choosing the right schemes, and making informed healthcare choices. In 2026, Merdeka Generation seniors can benefit from a range of subsidies, including outpatient care, MediShield Life, and CHAS. Planning ahead ensures you access the full benefits available, helping you reduce out-of-pocket expenses while maintaining quality healthcare during retirement.

    Understanding the Healthcare Support Landscape for Retirees

    Singapore’s healthcare system blends public and private options to ensure accessible and affordable care for seniors. Schemes like MediShield Life, MediSave, and CHAS form the backbone of government support, with specific schemes tailored for the Merdeka Generation. As a senior, your goal should be to understand these options thoroughly and use them to your advantage.

    In 2026, the government continues to enhance these schemes, making it easier for seniors to enjoy comprehensive coverage. Knowing which benefits you qualify for and how to claim them can prevent unnecessary expenses. This approach also reduces the risk of missing out on subsidies you are entitled to.

    How to Maximise Healthcare Subsidies During Retirement

    Maximising healthcare subsidies requires a strategic approach. Here are three practical steps to help you make the most of available schemes:

    1. Check Your Eligibility and Register for Schemes Early
      Ensure you are registered for schemes like the Merdeka Generation Package and CHAS. Eligibility criteria for the Merdeka Generation include being born between 1950 and 1959, and having lived in Singapore for at least 3 years. You can verify your qualification through the how to check if you qualify for the Merdeka Generation Package in 2026. Registering early guarantees you start enjoying subsidies without delay.

    2. Utilise Your Benefits at Approved Healthcare Providers
      Make it a habit to visit clinics under the Community Health Assist Scheme (CHAS) and polyclinics that participate in government schemes. These providers offer subsidised outpatient care, including chronic disease management. If you’re unsure whether your preferred doctor accepts CHAS subsidies, consult their website or ask directly to avoid unnecessary out-of-pocket costs.

    3. Plan Your Healthcare Budget and Keep Track of Claims
      Create a simple healthcare budget that includes subsidies, Medisave contributions, and out-of-pocket expenses. Keep records of your claims to monitor your subsidy usage. Regularly reviewing your healthcare spending ensures you stay within your budget and identify opportunities for savings.

    “Being proactive about your healthcare subsidies can save hundreds of dollars annually. It’s about knowing your options and making informed choices at each step.” — Senior Financial Advisor

    Additional Tips for Optimising Healthcare Savings

    • Use your Medisave account wisely, especially for outpatient treatments and certain approved procedures.
    • Consider supplementing with private insurance if your healthcare needs are complex or require specialised care.
    • Stay healthy by maintaining a balanced diet, exercising regularly, and managing chronic conditions. Prevention helps you avoid costly treatments later.

    Common Pitfalls and How to Avoid Them

    Many seniors make mistakes that limit their access to subsidies or lead to unnecessary expenses. Here’s a quick comparison of common pitfalls and how to prevent them:

    Mistake How to Avoid Consequence of Mistake
    Not registering for schemes early Check eligibility and register online or at clinics Missed subsidies, higher out-of-pocket costs
    Visiting non-participating clinics Confirm with providers if they accept CHAS or Merdeka Generation subsidies Paying full price for outpatient services
    Ignoring claim limits Keep track of claims and subsidies used Running out of subsidies prematurely, paying more later
    Overlooking preventive care Regular health screenings, healthy lifestyle Increased risk of serious illnesses and costs

    How the Merdeka Generation Package Supports Your Healthcare Needs

    The Merdeka Generation Package offers a comprehensive set of benefits tailored for seniors born between 1950 and 1959. In 2026, it continues to be a vital resource for reducing healthcare costs.

    Key benefits include:

    • Additional outpatient care subsidies at public clinics and polyclinics
    • Higher MediShield Life subsidies to lower premiums
    • Top-ups to Medisave accounts for future healthcare needs
    • Access to the Community Health Assist Scheme (CHAS) for outpatient subsidies

    To maximise these benefits, ensure your details are updated with the latest application process. This guarantees you receive all subsidies you qualify for without delays.

    Simplify Healthcare Planning for Retirement Success

    Effective healthcare planning is about more than just applying for subsidies. It involves understanding your health needs, choosing suitable providers, and setting aside funds for unexpected expenses.

    • Regular health checks can catch issues early and reduce long-term costs.
    • Consider combining government subsidies with private insurance for broader coverage.
    • Use tools like the insurance calculator to compare plans and premiums.

    By building a robust healthcare budget, you can face the future with confidence. Remember, the goal is to enjoy your retirement with minimal worries about health-related financial stress.

    Building a Healthcare Savings Strategy That Works

    Creating a sustainable healthcare plan involves combining subsidies, Medisave, and personal savings. Here are some techniques and mistakes to watch out for:

    Technique Mistake Result
    Regularly review your Medisave and subsidy claims Neglect to update your details or check claim limits Missed opportunities for savings or claim rejection
    Use approved providers for outpatient care Visiting unapproved clinics Higher costs and no subsidies
    Keep a record of healthcare expenses Failing to track spending Overspending or missing subsidy benefits

    Practical process for saving on healthcare costs

    1. Verify your eligibility for the Merdeka Generation Package and other schemes.
    2. Register for schemes like CHAS and MediShield Life if not yet done.
    3. Schedule regular health screenings and utilise subsidised outpatient care.

    By following these steps, you can ensure you receive all the support available in 2026.

    Final Tips for Smarter Healthcare Spending

    • Always check if your healthcare provider accepts subsidies before treatment.
    • Use your Medisave for approved outpatient procedures to preserve cash.
    • Stay proactive about your health to avoid costly emergency treatments.

    Remember, the key to maximising your healthcare subsidies is staying informed and disciplined. In retirement, every dollar saved on healthcare is a dollar you can spend on enjoying your passions.

    Keeping Your Healthcare Support Strong in Your Retirement Years

    Retirement in Singapore can be fulfilling and worry-free, especially when you make the most of government support schemes. Staying updated on current benefits, registering early, and maintaining a healthy lifestyle will help you stretch your retirement funds further. Remember, healthcare subsidies are designed to support you, but only if you actively claim and use them.

    Take the time to review your eligibility each year. Talk to trusted financial or healthcare advisors if needed. Applying the right strategies today prepares you for a healthier, more comfortable tomorrow. Your retirement years are your time to enjoy life—let smart planning ensure they are worry-free and full of joy.

  • How to Update Your Details to Ensure Continued Merdeka Generation Benefits in 2026

    How to Update Your Details to Ensure Continued Merdeka Generation Benefits in 2026

    When the clock strikes 2026, it’s time for Merdeka Generation seniors and their caregivers to ensure their benefits remain uninterrupted. The Merdeka Generation Package offers valuable healthcare subsidies, outpatient care, and financial support tailored for those born in the 1950s. Staying updated is essential to continue enjoying these perks, especially since government schemes may change or expand. This guide simplifies what you need to do to update your details and secure your benefits for the year ahead.

    Key Takeaway

    To keep enjoying your Merdeka Generation benefits in 2026, seniors and caregivers should verify their eligibility, update their details with government agencies, and stay informed about scheme changes. Simple steps now can prevent disruptions later, ensuring healthcare, subsidies, and financial support are always accessible when needed.

    Understanding the importance of updating your Merdeka Generation details

    The Merdeka Generation Package is a significant part of Singapore’s effort to support seniors. It provides subsidies for outpatient treatments, outpatient specialist care, and additional health coverage. However, these benefits are not automatic for life. They depend on your current details and eligibility. Changes in your circumstances or inaccuracies in your records might affect your benefits.

    Updating your details for 2026 is straightforward but essential. It ensures that government systems recognise your continued eligibility and that you receive the latest benefits. This process also helps avoid any gaps in your healthcare or financial support. Staying proactive keeps your healthcare secure and your mind at ease.

    Confirming your eligibility for the 2026 benefits

    Before updating your details, it’s vital to confirm if you still qualify for the Merdeka Generation Package. Generally, eligibility hinges on:

    • Being born between 1950 and 1959
    • Having Singapore citizenship
    • Being registered with the relevant government schemes

    To verify your status, visit the official Merdeka Generation portal, which provides a simple online check. If you find that you’re eligible, the next step is to ensure your details are accurate and up to date.

    How to update your details for 2026 smoothly

    Updating your information is a key step that can be completed in just a few easy steps:

    1. Visit the official Merdeka Generation update portal
      Head over to merdekageneration.sg/how-to-update-your-details-to-ensure-continued-merdeka-generation-benefits-in-2026. The portal is designed for seniors and caregivers to make updates without hassle.

    2. Login using your SingPass or other verified credentials
      SingPass is the most common way to securely access government services. If you haven’t set up your SingPass, do so before starting the update process. This step ensures your personal details are protected.

    3. Review and update your personal information
      Check your name, NRIC, contact details, and address. If you’ve moved or changed your contact number, update these fields. Accurate information guarantees you receive the latest notifications and benefits.

    4. Confirm your health and housing details
      If there have been changes in your health status or housing situation, update these as well. This helps tailor your benefits to your current circumstances.

    5. Submit your updates and wait for confirmation
      After submitting, you will receive an acknowledgment email or message. Sometimes, the system may require additional documentation or verification, especially if there are significant changes.

    Pro tip: Keep a copy of your updated details for your records. This makes future updates or inquiries easier.

    Additional tips to ensure benefits are maximised

    Updating your details is just the start. To make the most of your Merdeka Generation Package, consider these tips:

    • Check your healthcare subsidies regularly—they may change or increase in 2026. Knowing what subsidies you qualify for helps you plan medical visits and reduce costs.
    • Review your MediSave and MediShield Life status—these are vital for covering hospital and specialist bills.
    • Explore supplementary schemes such as Silver Support or ElderShield—these can provide extra financial support if needed.
    • Stay informed about scheme updates—government policies evolve, and new benefits may become available. Visit merdekageneration.sg regularly for updates.
    • Involve family members or caregivers in your update process—sometimes, they can assist with online registrations or document submissions.

    “Proactivity is key to ensuring your healthcare benefits don’t lapse. Regularly reviewing and updating your details ensures you always receive the support you deserve.” — Singapore’s aging support expert

    Common mistakes to avoid when updating benefits

    To ensure a smooth process, watch out for these pitfalls:

    Mistake Why it matters How to avoid
    Forgetting to update after moving Your benefits may be sent to the wrong address Always update your address promptly after moving
    Using outdated contact info You might miss important notifications Confirm your contact details during each update
    Not verifying eligibility You might lose benefits unknowingly Double-check your eligibility status before updating
    Submitting incomplete documentation Your update could be delayed Prepare all necessary documents before starting
    Ignoring scheme announcements Missing out on new benefits or changes Regularly check official channels for updates

    By paying attention to these details, you can prevent delays and ensure your benefits are always aligned with your current situation.

    How to prepare for scheme changes in 2026

    Government schemes often undergo updates. To stay ahead:

    • Visit official portals frequently, especially merdekageneration.sg, for the latest announcements.
    • Review your benefits annually, not just at the start of each year.
    • Engage with community support programmes—many community centres organise sessions explaining new schemes.
    • Consult trusted financial advisors or caregivers for personalized guidance, especially if your circumstances change.

    Being informed helps you adapt quickly and ensures you continue to enjoy the full range of benefits.

    Planning ahead for a comfortable retirement

    Updating your details is part of broader retirement planning. Consider:

    • Assessing your retirement savings—ensure your CPF and personal savings are sufficient for future healthcare needs.
    • Exploring insurance options—additional private health plans can supplement government subsidies.
    • Thinking about housing options—downsizing or upgrading may impact your benefits and costs.
    • Creating a monthly budget that accounts for healthcare, daily expenses, and leisure—maintaining a balanced budget helps retire comfortably.

    The key is to stay proactive, informed, and adaptable.

    Keeping your Merdeka Generation benefits current for 2026 and beyond

    Regularly updating your details and understanding scheme changes ensures your healthcare and financial support remain seamless. Remember, government benefits are designed to serve you better when your records are accurate and up to date. Take a moment to review your information today and set a reminder for annual checks. Retirement is a journey best navigated with confidence, clarity, and the right support. By staying engaged, you empower yourself to enjoy your golden years with peace of mind.